An original illustration for FYI4Men about the home and the financial decision.
A house can start to feel like yours before you have made an offer. You picture the people around the table, the room you would change, the years you could spend there. If the asking price drops, it is easy to feel that the decision just got easier.
Maybe it did. But the price is only part of what you are committing to. The loan, the ongoing bills and what you would otherwise do with your money belong in the same conversation. So does the life you want the house to support.
Our FYI4Men video walks through a hypothetical rent-versus-buy comparison. Here, we open up the numbers, including interest, rising property taxes and upkeep, and the discipline behind investing the difference. The result changes with the assumptions. That is useful to see before treating either choice as the obvious answer.
Watch Rent vs Buy: Investing the Difference Over 20 Years
A lower price can still mean a higher payment
Consider two hypothetical purchases with 20% down and a 30-year fixed mortgage. A $500,000 home financed at 3% means a $400,000 loan and about $1,686 a month in principal and interest. A $450,000 home financed at 6.5% means a $360,000 loan and about $2,275 a month.
The purchase price fell 10%, yet the principal-and-interest payment rose about $589, or 35%. These are teaching examples, not current loan quotes or a claim about a particular market.
And neither payment tells you the full cost of living there. The CFPB explains that mortgage payments often include taxes and insurance beyond principal and interest. Maintenance, repairs and utilities need room in the budget too.
Give both choices the same money
For the comparison, both paths start with $103,500, with emergency reserves kept outside the example. The buyer puts $90,000 down on the $450,000 home and spends $13,500 on assumed closing costs. The renter puts $2,300 into a refundable deposit and invests the remaining $101,200.
The rental is assumed to provide comparable housing. That matters: comparing a small apartment with a much larger house would mix a financial decision with a lifestyle upgrade.
| Item | Buyer | Renter |
|---|---|---|
| Mortgage principal and interest | $2,275.44 | Not applicable |
| Rent | Not applicable | $2,300.00 |
| Property tax | $600.00 | No separate charge modeled |
| Insurance | $150.00 | $20.00 |
| Maintenance actually spent | $300.00 | No separate allowance |
| Utilities | $250.00 | $250.00 |
| Total housing allocation | $3,575.44 | $2,570.00 |
The renter initially invests the $1,005.44 monthly gap. Both paths receive the same housing-and-saving allowance each month, equal to whichever housing allocation is higher. The cheaper path invests what remains at month-end. That rule would also let the buyer invest a surplus if ownership became cheaper.
The allowance can rise over time. This keeps cash resources equal within each case, but it does not show that a household with a fixed income could afford either path. Also, principal repayment builds equity, so the table is a cash allocation, not a list of money that disappears.
The bills keep coming after closing
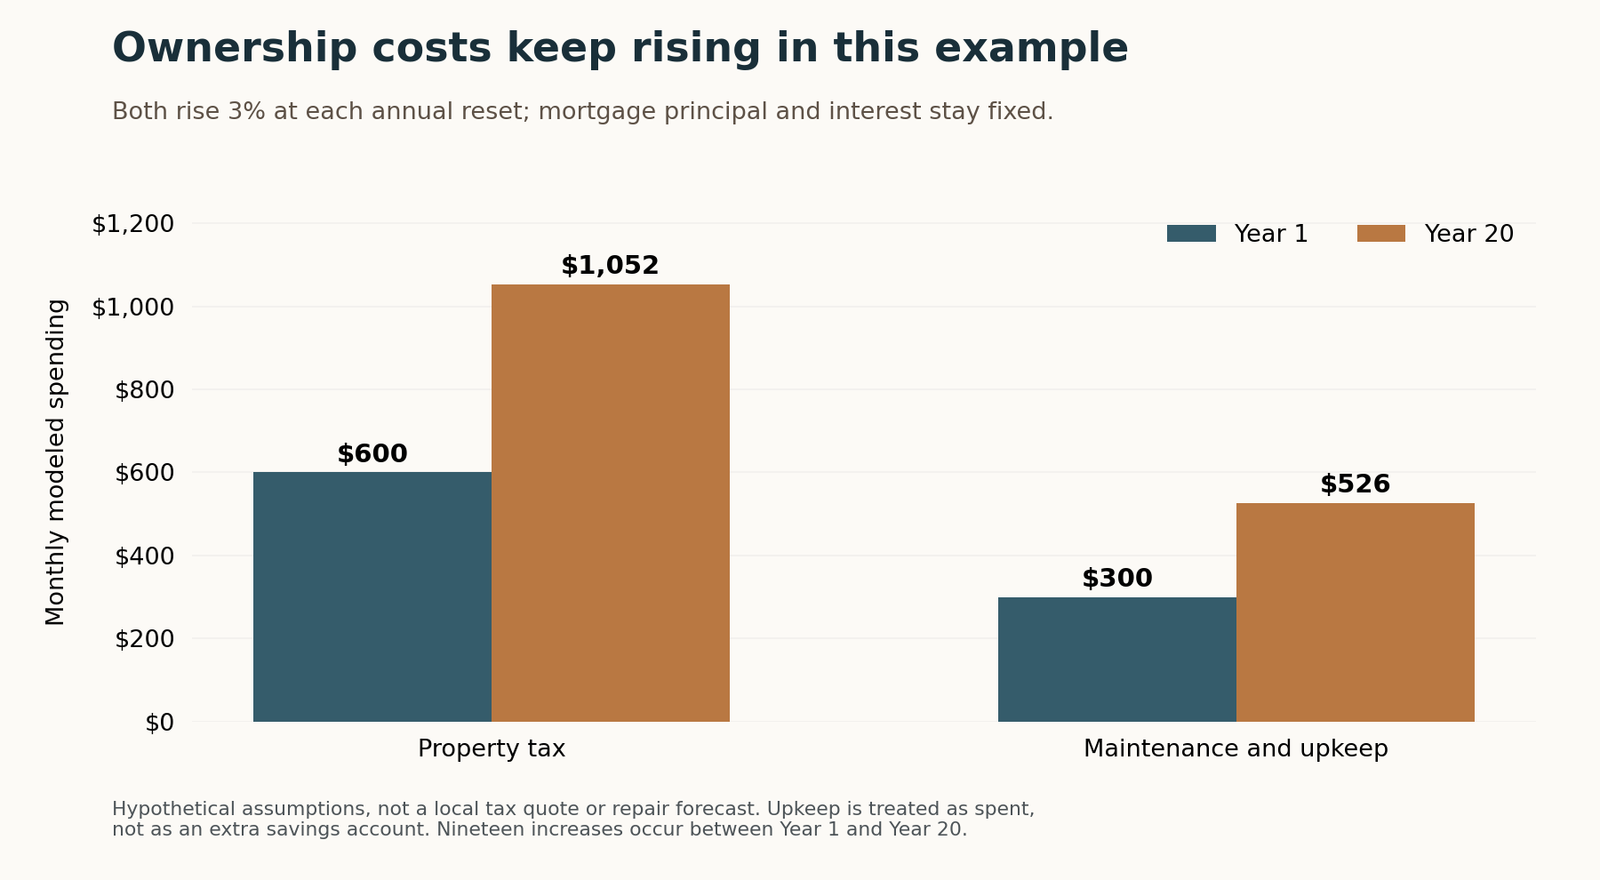
In this example, rent and every non-mortgage housing cost increase 3% annually, beginning in month 13. The fixed mortgage keeps its combined principal-and-interest payment unchanged, although the split between those two parts changes.
Property tax starts at $600 a month and reaches about $1,052 in year 20. Maintenance starts at $300 and reaches about $526. Over twenty years, those two lines add up to roughly $193,467 in property tax and $96,733 in upkeep. Maintenance here means money actually spent, not an untouched repair reserve that should still count as an asset.
Mortgage interest totals about $113,526 over five years and $386,502 over twenty. By the twenty-year point, about $159,605 of principal has been repaid. That principal is already reflected in the smaller remaining loan balance; adding it to equity again would count it twice.
The renter pays about $741,622 in rent over twenty years, plus renters insurance and utilities. Both paths buy somewhere to live throughout that time. Comparing rent alone with mortgage interest alone would leave too much out.
What remains after five or twenty years
We assume the home grows in value by 3% a year and costs 6% of its sale price to sell. Those are illustrative inputs, not a forecast or a standard commission quote. The five-year and twenty-year results are separate exits from the same starting point. There is no sale at year five followed by another fifteen years of ownership.
At five years, the assumed home value is about $521,673. Subtract roughly $31,300 in selling costs and the $337,000 remaining mortgage, and the buyer has about $153,373. At twenty years, an assumed $812,750 sale price, less $48,765 in selling costs and a $200,395 loan balance, leaves about $563,590.
For the renter, we test three constant effective annual investment returns: 5%, 7% and 10%, after fees but before personal income taxes, with distributions reinvested. No specific fund or portfolio is being modeled.
| Path or investment return | After 5 years | After 20 years |
|---|---|---|
| Buyer with 3% home growth | $153,373 | $563,590 |
| Renter at 5% | $194,581 | $533,980 |
| Renter at 7% | $210,614 | $737,645 |
| Renter at 10% | $236,829 | $1,197,762 |
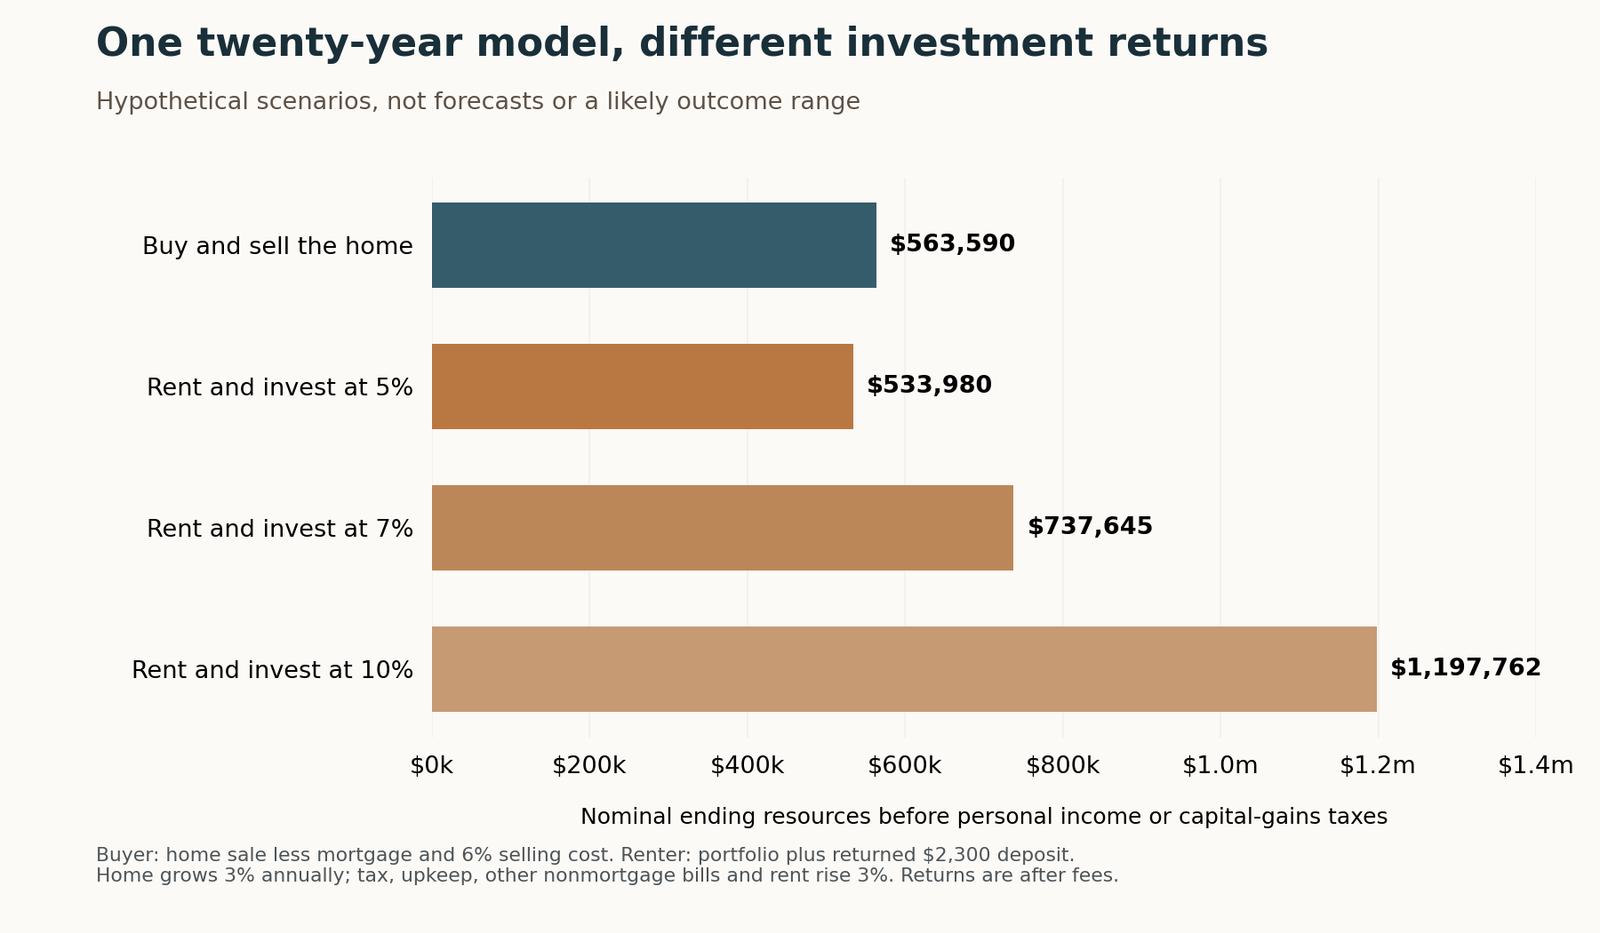
Buyer figures are net sale proceeds. Renter figures are investments plus the returned $2,300 deposit. They include money contributed along the way, not just profit. All are future dollars, without adjusting for inflation.
At five years, renting finishes ahead in these three cases. At twenty years, buying finishes ahead of the 5% case, while renting finishes ahead at 7% and 10%. The house assumptions stay unchanged as the investment return changes.
These are hypothetical sensitivities, not forecasts, probabilities or a confidence range. Actual returns will not arrive in a smooth line, can be negative, and can disappoint when you need the money. Investor.gov explains the risk of losses when investing in stocks; the model does not promise that any investment will deliver one of these rates.
Investing the difference requires a real habit
The renter's monthly contribution does not stay at $1,005.44. As rent and other bills rise while mortgage principal and interest stay fixed, it shrinks to about $846 in year five, $618 in year ten and $48 in year twenty. The twenty-year contributions total about $136,602.
At the hypothetical 5% return, investing the initial cash and every monthly gap produces about $533,980, including the deposit. Keeping the same initial investment but spending the monthly gaps leaves about $270,814. The roughly $263,166 difference includes both the saved contributions and their growth. It is not all investment profit.
Spending that money buys more consumption along the way. There may be things you value enough to choose that. But a plan to rent and invest only works as described if the investing actually happens. An automatic transfer can help turn the intention into a routine.
A mortgage creates its own regular commitment to principal repayment. That can be useful discipline, provided the payment leaves you enough room for the rest of your life. The interest and other ownership expenses still need to be paid.
Small changes can change the result
The starting $300 monthly upkeep assumption is 0.8% of the purchase price per year, and it excludes extraordinary repairs. Raise it to $375 a month, or 1% initially, with the same annual increases, and the twenty-year renter result at 5% rises to about $572,969. That passes the buyer's $563,590.
Under the equal-allowance rule, higher ownership spending gives the renter more to invest. The buyer's sale proceeds are not reduced again for expenses already paid. The shared budget is higher in this sensitivity, so it should not be mistaken for the same fixed household budget.
Real properties bring less tidy costs. This model excludes HOA fees, mortgage insurance, refinancing, extraordinary repairs, special assessments and moving-cost differences. It also excludes investment income taxes, home-sale gains taxes and homeowner income-tax benefits. Property taxes are included. Local rents, insurance, assessments, repairs and tax treatment could materially change the comparison.
Make room for the life you are choosing
Owning can give you roots, control over your space and a place for family life to unfold. Renting can give you flexibility when work, relationships or the place you want to live are still changing. Those benefits deserve weight even when a spreadsheet cannot give them a dollar value.
Before deciding, get specific:
- How long are you likely to stay, and what could make you leave sooner?
- What will this particular home cost after insurance quotes, taxes, inspections and repairs?
- What emergency cushion remains after closing, and what happens if income falls?
- If you rent, how much will you actually invest each month?
- What would you willingly pay for the stability of owning or the freedom of renting?
The CFPB's homebuying budget guide is a useful place to build out those costs. Use actual local figures, and get qualified financial or tax advice for your situation rather than treating this example as a recommendation.
A home should have room for the people and priorities you care about. Your budget needs room for them too. What would make buying or renting right for your life? Watch the video and tell us in the comments.

Leave a Reply